
The 2018 change was a structural choice
DMM.com announced its conversion from a stock company to a Japanese limited liability company, or godo kaisha, on May 25, 2018. Its absorption of DMM.com Lab took effect on June 1. The corporate history records the restructuring in June.
A godo kaisha does not issue the publicly tradable shares used for an ordinary stock-market listing. That makes the current corporate form a practical obstacle to listing DMM.com as it stands, but not an irreversible one. A conversion or wider reorganization could create a different route if management chose to pursue it.
The legal form explains how the business is organized. It does not, by itself, explain the full commercial reason for remaining private.
A portfolio of experiments can benefit from flexible capital
DMM's business-creation and recruitment materials describe a broad portfolio and an emphasis on developing new services. Its acquisition materials also present M&A as a way to bring outside businesses into the group.
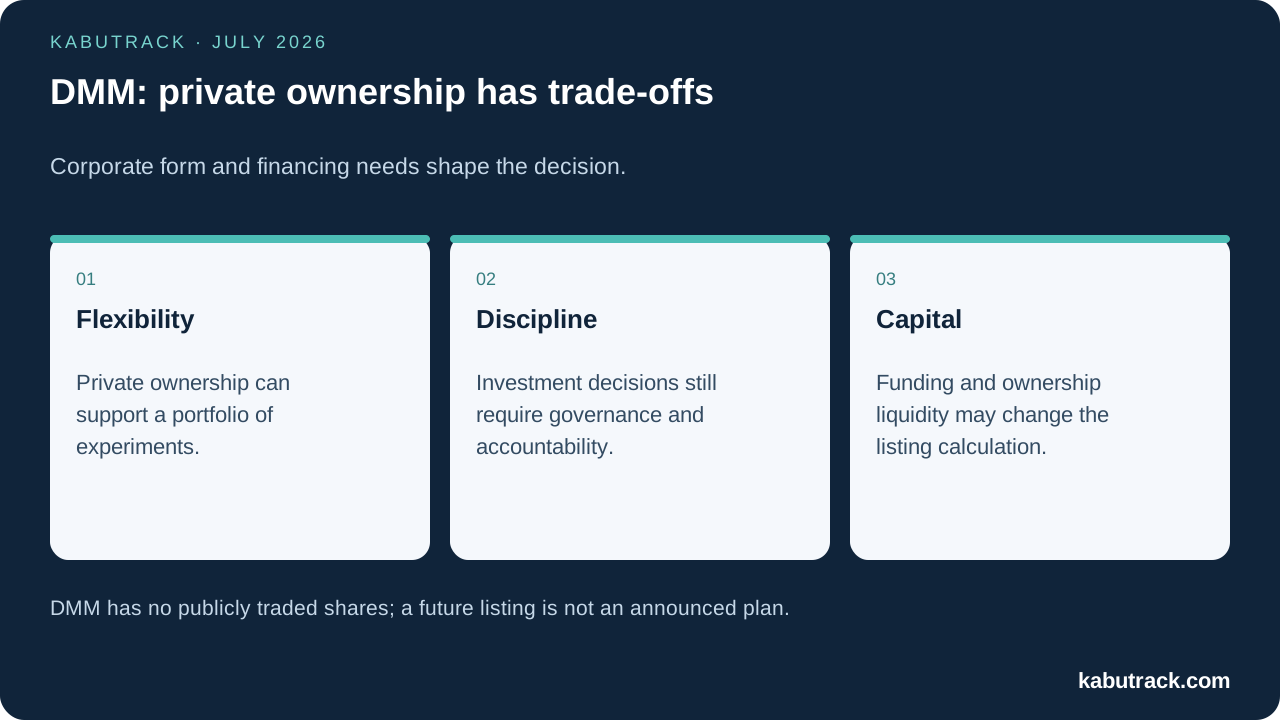
Such a model involves uneven results. Some ventures mature, others require investment for years and some are closed. Private ownership may give management more latitude to move resources between them without explaining each short-term earnings fluctuation to public shareholders.
That freedom is useful only if the group allocates capital well. Fast decisions can shorten the time needed to test a service; they can also allow weak ventures to absorb resources for too long. The relevant questions are who approves investment, how losses are limited and when management decides that an experiment has failed.
DMM's public descriptions make this model plausible. They do not supply a complete, audited account of its business-level profitability or prove that any particular venture funds the rest of the group.
Private does not mean free of financial obligations
Article 440 of Japan's Companies Act concerns publication of annual balance sheets by stock companies. A godo kaisha does not have the same stock-company publication obligation under that provision.
That difference should not be expanded into a claim that DMM has no accounting, tax or legal duties. Nor does limited public disclosure establish the amount of retained earnings, available cash or borrowing capacity.
The group could use internal cash generation, borrowing or other private financing. Public information does not allow a reliable ranking of those sources or a conclusion that abundant retained earnings are the sole reason it has avoided an IPO.
The trade-offs extend beyond quarterly reporting
Remaining private reduces the need to accommodate public-market expectations, but it also limits access to a liquid equity market. Owners may have fewer ways to realize the value of their interests, and the group lacks an ordinary publicly traded share that can be used as acquisition consideration.
Public disclosure can impose discipline by making capital allocation and weak performance easier to challenge. A private group must obtain that discipline from its governance, lenders, owners and internal processes instead.
Succession is another consideration. A model built around entrepreneurial decisions needs a way to preserve judgment and accountability as leadership changes. Corporate form alone cannot solve key-person risk.
FANZA requires controls, rather than a simple explanation for non-listing
DMM's connection with adult-content services raises questions about rights, consent, payment access and the boundaries among group businesses. Those questions would require clear disclosure and effective controls in any assessment of public ownership.
They do not establish an automatic legal ban on listing. Public materials also do not prove that adult content is the principal reason DMM remains private. Assigning one explanation to a group with many businesses would exceed the available evidence.
A credible listing case would need to clarify the portfolio, its sources of earnings, governance and material operating risks. Those requirements would matter regardless of the industry's public image.
What could make a listing attractive?
A major capital requirement, demand for liquid acquisition currency, ownership liquidity or succession planning could change the calculation. A more focused portfolio with understandable consolidated earnings could also make a public offering easier to explain.
Conversely, adequate private funding and a continuing preference for rapid business experimentation could support the present arrangement. Neither outcome is an announced plan.
Public investors cannot buy DMM shares today. The broader lesson is to assess whether a company's financing structure serves its operating model, and whether that model has enough discipline to turn freedom into durable returns.
Related Pages
Sources
- DMM.com Business Creation Department, “Organization Overview”
- DMM.com, “Kamechoku recruitment page” (descriptions of more than 60 businesses and services and of new-business development)
- DMM.com, “Notice regarding DMM.com becoming an LLC and completing an absorption-type merger”
- DMM.com, “Newly released ‘DMM M&A’ page presenting DMM’s unique M&A guidelines”
- DMM.com official website (route to the adult service FANZA)
- e-Gov Law Search, “Companies Act”